A 2019 FCA report found that some customers were being overcharged more than £1,000 in interest charges. This report continues to gain attention, as potential consumer claims against finance lenders build momentum.
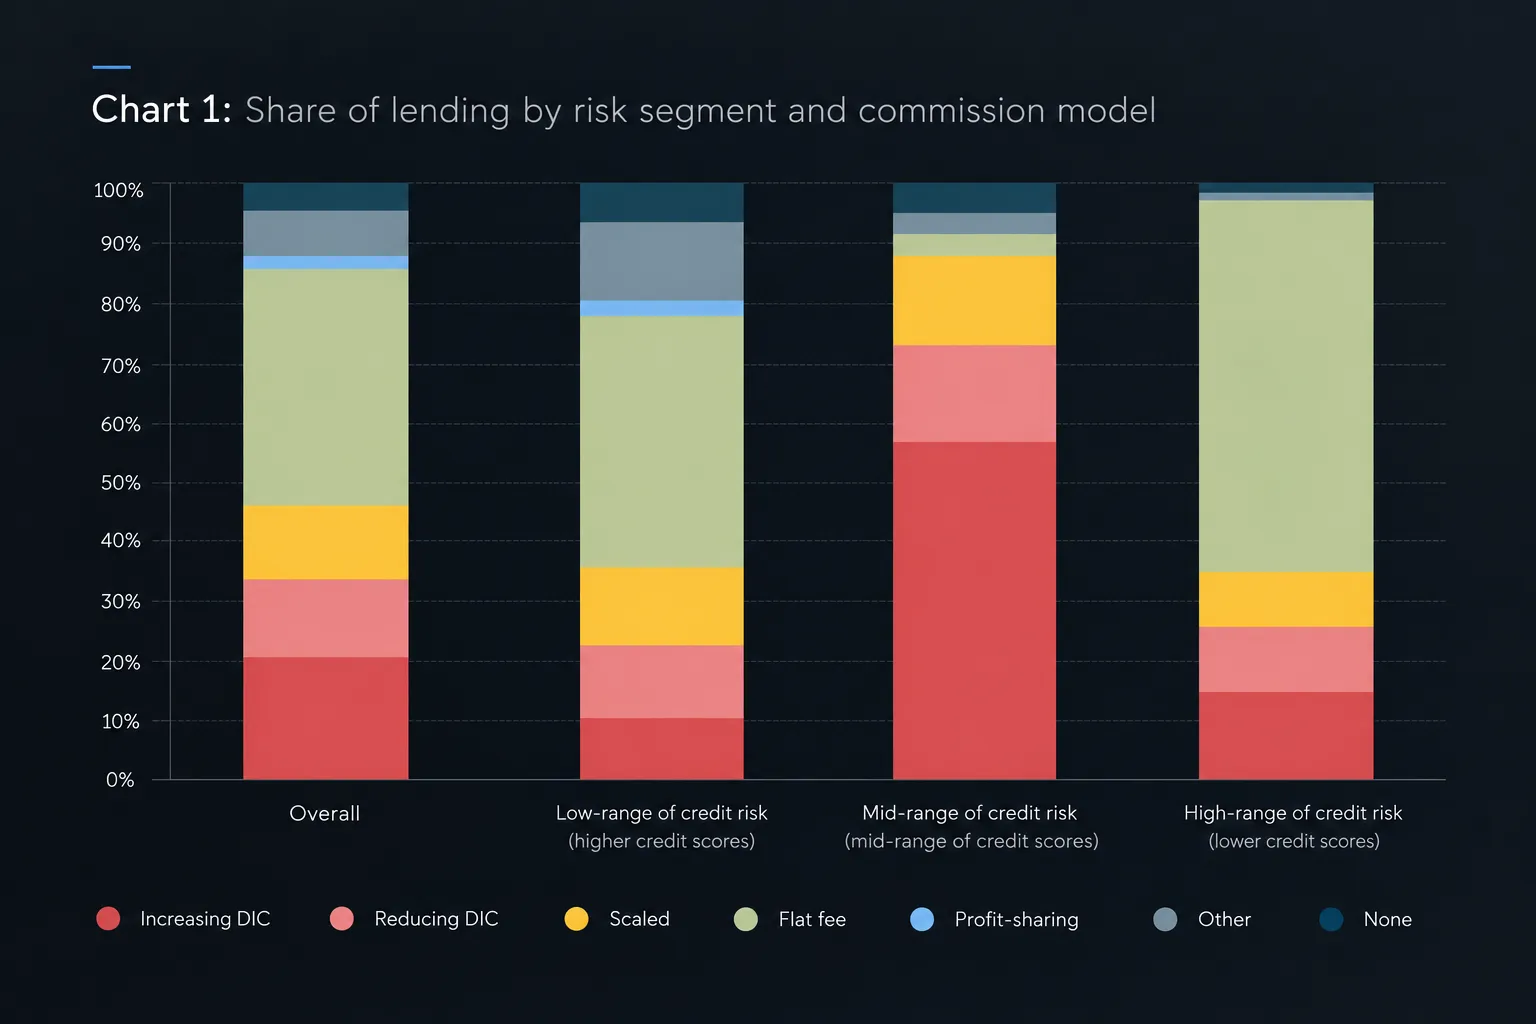
Here are 5 key takeaways:
- “…the way commission arrangements are operating in motor finance may be leading to consumer harm on a potentially significant scale.”
- “…we estimate that commission models which allow broker discretion over the interest rate could be costing customers £300m more annually when compared against a baseline of Flat Fee models.”
- “The difference between the average and highest commission was around £2,000 for the DiC [Difference in Charges] and Scaled models, compared to £700 for the Flat Fee commission model.”
- “We estimate that on a typical motor finance agreement of £10,000, higher broker commission under the Reducing DiC model can result in the customer paying around £1,100 more in interest charges over the four-year term of the agreement.”
- “Difference in charges models (Increasing and Reducing) were more prevalent in the mid-range of credit risk, accounting for around 75% of lending within that segment.”
On January 28, 2021, the FCA introduced new rules to prohibit the discretionary commission model for regulated credit agreements.
Christopher Woolard, the FCA’s Interim Chief Executive, said:
We estimate that consumers could save £165 million because of today’s action.
Read the full FCA report.